国库券收益率因新发行浪潮考验投资者需求而大幅上升,对隔夜融资市场的稳定性构成威胁。
Treasury-bill yields have risen sharply as a wave of new issuance tests investor demand, posing a threat to the stability of overnight funding markets.
这种动态在本周的八周期国库券拍卖中得以体现,其需求创历史新低,收益率达到4.05%,为一年多来的最高水平——这表明投资者不愿将资金投入日益增长的国库券供应中,以资助不断扩大的赤字以及未来几个月美联储利率路径的不确定性。
That dynamic showed up in the eight-week bill auction this week, with its record-low demand and yields at 4.05%, the highest in over a year — evidence of investor reluctance to pile into the growing supply of bills to fund the widening deficit and an uncertain path of Federal Reserve interest rates over the coming months.
然而,这种压力尚未蔓延至仍充斥着现金的融资市场,使其面临国库券债务中日益明显的压力风险。
That pressure, however, has yet to spill into the funding market that remain flush with cash, leaving it vulnerable to the growing stress evident in T-bill debt.
“本月,多种竞争力量正在塑造货币市场,”巴克莱集团策略师塞缪尔·厄尔在给客户的一份报告中写道。“视角不同,市场似乎正陷于两种截然不同的叙事之间:一方面是新兴融资压力的迹象,另一方面则是出人意料的平静状况。”财政部数据显示,截至10月前半月,财政部已净发行近1000亿美元的国库券。巴克莱估计,未来六周的供应量将超过3200亿美元。
“Several competing forces are shaping money markets this month,” Barclays Plc strategist Samuel Earl wrote in a note to clients. “Depending on where one looks, the market appears caught between two very different narratives: signs of emerging funding pressure on one hand, and surprisingly subdued conditions on the other.”Treasury has already issued nearly $100 billion of net T-bills through the first half of October, TreasuryDirect data show. Barclays estimates coming supply will exceed $320 billion over the next six weeks.
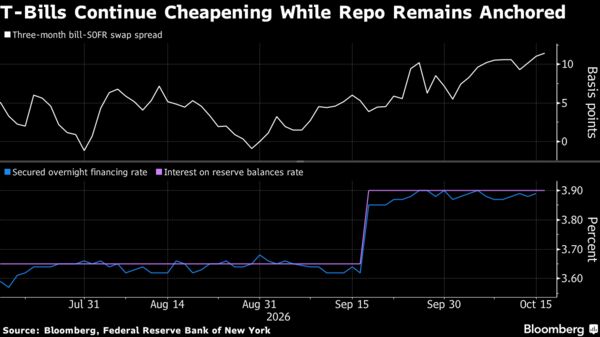
这导致国库券利率相对于担保隔夜融资利率(SOFR)掉期扩大,而SOFR是一种被视为无风险利率的市场化指标。然而,在10月的大部分时间里,SOFR的交易价格处于或低于准备金利息率(IORB),这表明尽管国库券市场压力在增加,但流动性仍然充裕。
This has caused bill rates to widen relative to swaps on the Secured Overnight Financing Rate, a market-based metric considered the risk-free rate. Yet for most of October, SOFR has traded at or below the interest on reserve balances rate, or IORB, suggesting liquidity remains abundant despite growing pressure in the bill market.
多种力量正在将市场拉向不同方向。货币市场基金作为国库券的最大买家,其资金流入正在放缓,而发行规模却在加速。与此同时,投资组合经理人变得“越来越防守”,根据厄尔的说法,他们更倾向于购买到期更短的债务,因为对美联储政策路径的不确定性在增加。
Several forces are pulling markets in different directions. Money-market funds, the biggest buyers of T-bills, have seen inflows slow just as issuance accelerates. At the same time, portfolio managers have become “increasingly defensive,” preferring to buy shorter maturity debt due to uncertainty surrounding the trajectory of the Fed’s policy path, according to Earl.
据富国银行(Wells Fargo & Co.)引用克兰数据(Crane Data LLC)的报告称,应税货币基金的所谓持续期定位已降至35.3天,年内下降3.4天,较4月中旬的峰值下降7.7天。降幅最明显的是国债基金,机构部分(这些基金的主要持有者)的到期日较4月末下降了近10天。
The so-called duration positioning of taxable money funds has fallen to 35.3 days, down 3.4 days year-to-date and down 7.7 days from the peak seen in mid-April, according to Wells Fargo & Co., citing Crane Data LLC. The drop was most pronounced among Treasury funds, with the maturities for the institutional segment, the major holders of these funds, down nearly 10 days from end-April.
这种转变在投资组合配置中表现明显,支持了对回购和浮动利率债务相较于固定利率国债票据的需求。事实上,根据美国银行(Bank of America Corp.)策略师的说法,联邦住房贷款银行(FHLB)债务发行量一直在上升,因为FHLBs正在替换到期债务并满足银行融资需求。发行主要集中在浮动利率票据上,而其他债券和贴现票据的供应则有所下降。
The shift is apparent in portfolio allocations, supporting demand for repo and floating-rate debt relative to fixed-rate Treasury bills. In fact, Federal Home Loan Bank debt issuance has been rising as FHLBs replace maturing debt and bank funding demand, according to Bank of America Corp. strategists. Issuance has been most concentrated in floating-rate notes, while supply in other bonds and discount notes has dropped.
然而,回购利率仍保持稳定,这可能是由于今年杠杆需求的结构性下降所致,因为相对价值和基础机会被压缩,减少了对经纪人中介融资的需求,巴克莱(Barclays)如此指出。
Repo rates have nevertheless remained stable, which may be due to the structural decline in leverage demand this year as relative value and basis opportunities compressed, reducing the need for dealer-intermediated financing, according to Barclays.
巴克莱还估计,补充杠杆比率约束的放松也导致了经纪人回购账本的扩张,这使得所谓的全球系统重要性银行(G-SIBs)——即大型金融机构——能够将其回购和逆回购余额在9月前增加约3000亿至3500亿美元。
Dealer repo books have also expanded following the relaxation of supplementary leverage ratio constraints, which Barclays estimates has allowed so-called G-SIBs, large financial institutions, to grow their repo and reverse repo balances by about $300 billion to $350 billion through September.
虽然现金充裕和投资者对最短期限的偏好有助于稳定回购市场,但这并非没有风险。
While the abundance of cash and investor appetite for the shortest-maturities has helped steady repo markets, it’s not without risks.
例如,鉴于融资市场没有明显的动荡,美联储可能决定长期暂停其储备管理购买。本周,美联储表示,这是连续第三个月不会为储备管理计划(RMPs)购买国债票据。
The Fed, for example, may decide to continue pausing its reserve management purchases for a prolonged period given the lack of apparent ructions in funding markets. The central bank this week said for the third straight month it won’t buy T-bills for RMPs.
这种立场可能会进一步加剧国债票据市场已经增长的压力,这种压力可能会蔓延到隔夜融资市场。
That stance threatens to further exacerbate the already growing pressure in the T-bill market that could spill over into the overnight funding market.
“资金市场持续疲软增加了美联储可能长期维持观望的风险,尤其是如果资产负债表容量在年底前的减少被杠杆需求下降所完全抵消甚至超过的话,”厄尔写道。
“Continued slack in funding markets raises the risk that the Fed could remain on hold for longer, particularly if the reduction in balance sheet capacity into year end is more than offset by declining leverage demand,” Earl wrote.