美国通胀以及人工智能行业的震荡在近期冲击了股市,一些投资者现在正在押注,科技股的更大幅度波动最终将蔓延至整个市场。
US inflation and tremors across the AI sector jolted stocks in recent days, and some investors are now betting that bigger swings in tech shares will finally spread to the broader market.
在周三之前,标普500指数已经连续53个交易日未出现1%的跌幅,这是自2020年1月以来的最长纪录。不仅波动率低,而且其表现异常稳定。
Before Wednesday, the S&P 500 Index had gone 53 sessions without a 1% drop, the longest stretch since January 2020. It’s not just that volatility was low, it had also been remarkably stable.
对许多交易者而言,当前的股票轮动是否会蔓延至更广泛的清算,从而导致波动率飙升,已经不再是“是否”的问题,而是“什么时候”的问题。尽管指数平静,但国债收益率居高不下,导致人工智能基础设施公司及其他相关行业出现波动率上升的局部现象。在宏观层面,伊朗和乌克兰战争持续推动的燃料和食品通胀几乎没有结束的迹象,这增加了对美联储加息的压力。
For many traders, it’s becoming more a question of when rather than if the current equity rotations spill over into broader liquidation, causing volatility to spike. Despite the calm indexes, elevated Treasury yields have contributed to pockets of higher volatility among artificial-intelligence infrastructure companies and other adjacent sectors. On a macro level, persistent fuel and food inflation, driven by wars in Iran and Ukraine that show little signs of ending, adds pressure on the Federal Reserve to raise rates.
“宏观环境仍然相当脆弱,”Moo Point Capital Management的管理合伙人Jeremy Wien表示。“我认为VIX目前应该反映出更多风险,但它并未这样定价,主要原因是直到周五之前,标普500指数(SPX)的走势并未显示出应有的波动。”虽然芝加哥期权交易所波动率指数(VIX)的看涨期权在全年大部分时间里看来是划算的,但VIX期货的微小波动描绘出不同的图景——持有押注波动率飙升的看涨期权看来变得昂贵。
“The macro environment remains quite fragile,” said Jeremy Wien, managing partner at Moo Point Capital Management. “The VIX was not pricing in nearly as much risk as I believe it should be at the moment, mostly because the SPX hasn’t until Friday moved in a manner that seems to warrant it.”While Cboe Volatility Index, or VIX, call options looked like a bargain for much of the year, the minuscule swings in VIX futures paint a different picture — one where it looks expensive to hold call options betting on a spike in volatility.
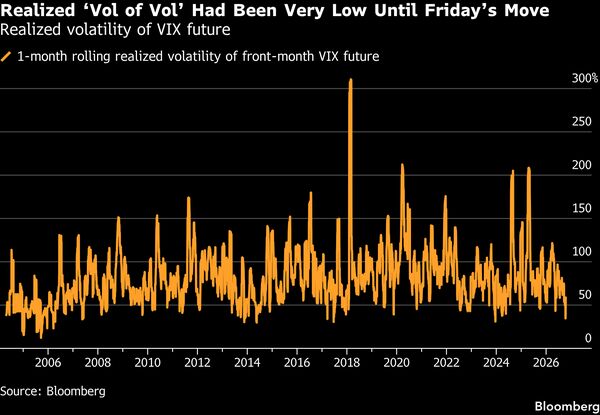
波动率的波动率——通过芝加哥期权交易所VIX的VIX指数(即VVIX)衡量——在周五之前一直徘徊在过去两年的最低水平,随后出现跳升。尽管如此,这并未阻止一些投资者建立长波动头寸。
The vol of vol — measured with the Cboe VIX of VIX Index known as VVIX — had been sitting around the weakest level of the past two years before jumping on Friday. Still, that hasn’t deterred some investors from building long volatility positions.
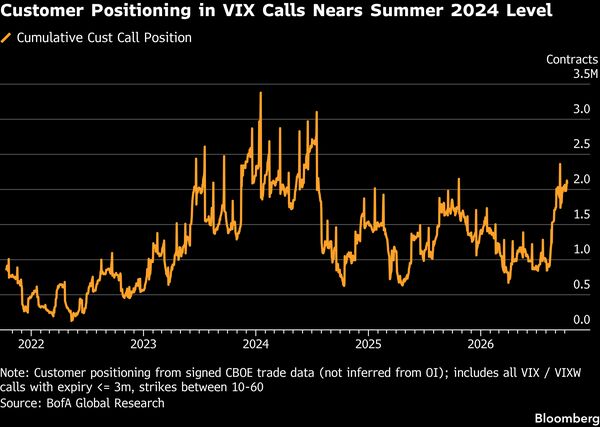
美国银行公司(Bank of America Corp.)的策略师最近指出,客户对VIX看涨期权的持仓急剧上升,正接近2024年夏季的水平,这凸显了对远期波动率的普遍需求。
Bank of America Corp. strategists recently wrote that VIX call positioning by customers has risen sharply and is approaching the levels of summer 2024, highlighting general demand for forward volatility.
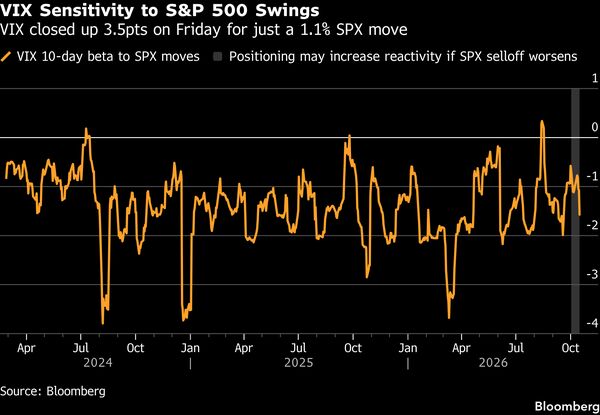
客户持有VIX看涨期权的一个连锁效应是,可能出现波动率伽玛挤压,即做空看涨期权的期权交易商需要买入期货以重新对冲头寸。这可能会加剧VIX的突然飙升,就像周五似乎发生的情况一样,当时波动率指标的盘中6点涨幅超过了对标普500指数近1.5%下跌的预期反应。
One knock-on effect of customers owning the VIX calls is the potential for a volatility gamma squeeze if option dealers who are short the calls need to buy futures to re-hedge their positions. That could exacerbate a sudden VIX surge as appeared to happen on Friday, when the 6-point intraday increase in the volatility gauge exceeded the expected reaction to a nearly 1.5% drop in the S&P 500.
策略人士估计,近月VIX期货出现10点的冲击性上涨,可能要求交易商买入相当于VIX期货日交易量90%的数量,以保持德尔塔中性。
The strategists estimate a 10-point shock increase in front-month VIX futures could require dealers to buy the equivalent of 90% of daily VIX futures volume to remain delta neutral.
“鉴于从主权收益率和能源成本上升,到即将举行的美国中期选举以及一个看似正从已危险的位置进一步恶化的紧张地缘政治环境等风险,美国股市出现显著下跌只是时间问题,”温说。“更不用说在上述升息环境下,AI生态系统有巨额融资需求。”不过,时机至关重要。长波动率交易者在2018年“波动末日”事件前学到的经验是,波动率和波动率的波动率可以在很长一段时间内保持异常低位。
“It is only a matter of time before we get a significant crack in US equities, given risks ranging from rising sovereign yields and energy costs to the upcoming US midterm elections and a fraught geopolitical environment that seems to be deteriorating from an already-perilous position,” Wien said. “Not to mention an AI ecosystem with substantial financing needs in the aforementioned rising-rate environment.”However, timing is key. As long volatility traders learned in the run-up to the Volmageddon episode in 2018, volatility and vol of vol can remain unusually low for very long periods.
而且VIX飙升往往是短暂的,交易者需要敏捷才能获利。所有这一切都助长了关于持有VIX看涨期权还是购买标普500或纳斯达克100指数看跌期权以对冲广泛市场抛售更好的永恒争论。
And VIX spikes are often brief, requiring a trader to be nimble in order to cash in. All of which feeds the perpetual debate over whether it’s better to own VIX calls versus buying S&P 500 or Nasdaq 100 Index puts to protect against a broad market selloff.
“由于现货/波动率关系不可预测,VIX在股市抛售时未必会飙升——至少不会像往年/周期那样剧烈——我宁愿在这里持有SPX(或QQQ)看跌期权,而不是VIX看涨期权,”温说。
“Because of an unpredictable spot/volatility relationship in which VIX may not necessarily spike during a selloff in equities — at least not as much as it has in prior years/cycles — I’d rather own SPX (or QQQ) puts than VIX calls here,” Wien said.
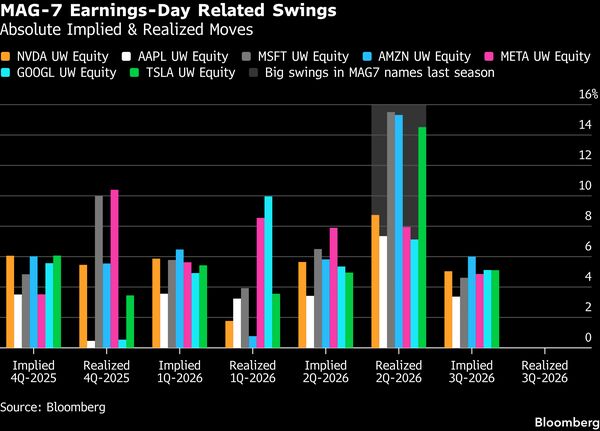
在最近的人工智能和半导体公司抛售之后,交易者将再次将目光投向科技巨头,尤其是“七巨头”公司,以了解市场在AI周期的这个阶段将如何消化盈利超预期和不及预期的情况。
After the recent selloff in AI and semiconductor companies, traders will be looking once again to the tech giants, especially the Magnificent 7 firms, as a guide to how the market is going to process earnings beats and misses at this stage of the AI cycle.
CoreWeave公司及其他AI基础设施公司因对为行业投资洪流提供资金的巨额借贷的担忧而出现的近期抛售只是提高了赌注。美国银行策略师指出,10月8日OpenAI宣布收入低于预期后,纳斯达克100指数期货当天出现的盘中下跌,展示了市场在更为重大的AI放缓情况下可能的反应。
The recent selloff in CoreWeave Inc. and other AI infrastructure companies on concerns about the massive borrowing to fund the flood of investment in the industry just raises the stakes. The Bank of America strategists noted that the intraday drop in Nasdaq 100 futures on Oct. 8 after OpenAI announced lower-than-expected revenue offered a glimpse into how the market may react in a more consequential AI slowdown.
鉴于当前因板块轮动导致的指数波动率低和相关性低,“如果当前现状发生变化且我们看到更激进且广泛的去风险化,指数看涨期权和看涨期权价差将提供廉价的宏观对冲,”凯特经纪公司经纪人安迪·肯特表示。
Given the current low index volatility and low correlations due to rotations between sectors, “index puts and put spreads offer cheap macro hedges should the current status quo change and we see more aggressive and broad-based de-risking,” said Andy Kent, a broker at Kyte.