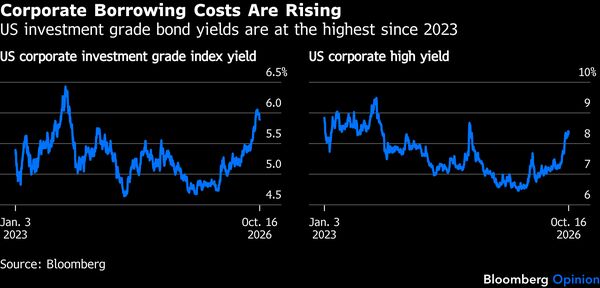
货币政策的“沉睡巨人”——企业信贷,终于开始苏醒。云计算服务提供商CoreWeave Inc.的债券本月下跌,其2032年到期票据的收益率一度高达15%。垃圾债和投资级债券的收益率分别升至2025年和2023年以来的最高水平。这意味着,作为央行给经济踩刹车、抑制通胀的关键渠道,企业信贷成本可能开始拖累增长。
Corporate credit, monetary policy’s sleeping giant, is finally stirring. Cloud computing service provider CoreWeave Inc.’s bonds dropped this month, sending yields on its 2032 notes as high as 15%. Yields for junk and investment-grade debt reached the highest since 2025 and 2023, respectively. The implication is that the cost of corporate credit, a key channel through which central banks tap the economy’s brakes to cool inflation, may start to weigh on growth.
这早有预兆。面对飙升的利率,美国企业直到现在一直以其韧性令投资者和经济学家感到意外。在新冠疫情期间锁定的超低借贷成本,意味着当美联储2022年开始加息并随后将利率推升至数十年来最高水平时,许多公司受影响微乎其微。在企业及其投资者享受多年无拘无束的利润增长之际,美联储实际上失去了通过收紧融资条件来对抗通胀的能力。
This has been a long time coming. US corporations have, until now, surprised investors and economists with their resilience in the face of soaring interest rates. Ultra-low borrowing costs, locked in during the Covid-19 pandemic, meant that many companies were minimally affected when the Federal Reserve started raising rates in 2022 and subsequently took them to the highest in decades. While companies and their investors delighted in years of unrestrained profit growth, the Fed essentially lost its ability to fight inflation by making financing conditions pricier.
传导机制如今正重新启动,这将影响未来的投资决策以及股票估值。9月重启加息的决策者需要审慎行事,以避免引发负面螺旋。
The transmission mechanism is now cranking back into action, and it will influence future investment decisions as well as stock valuations. Policymakers, who restarted rate hikes in September, need to move slowly to avoid creating a negative spiral.
企业通过负债和资产两端与利率互动。虽然随着旧债到期和贷款偿付,借贷成本重新定价的过程缓慢,但企业现金储备的收益率在美联储2022年首次加息时几乎立即跳升。
Companies interact with interest rates through both liabilities and assets. While borrowing costs have repriced slowly as old bonds matured and loans came due, the returns on corporate cash stockpiles jumped almost immediately when the Fed first hiked rates in 2022.
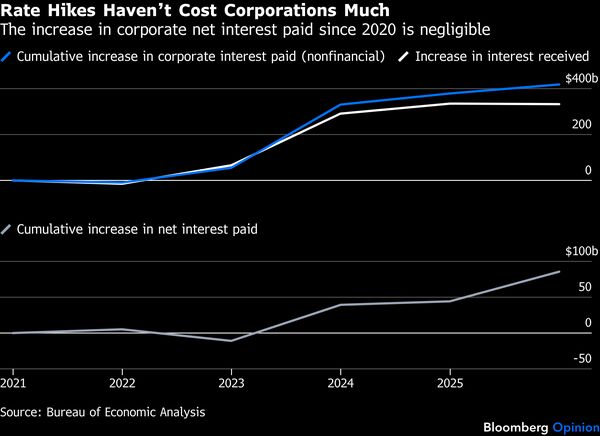
根据美国经济分析局的数据,令人难以置信的是,从2021年初到2022年底,公司实际上一直是加息预期的净受益者。此后,净利息支付开始缓慢上升,但影响微乎其微;五年间净成本上升了约860亿美元,而同期非金融企业利润却激增了约1.2万亿美元,达到约2.7万亿美元的税前利润。
It’s hard to believe, but companies were actually net beneficiaries of expectations around rate hikes from the beginning of 2021 through the end of 2022, according to Bureau of Economic Analysis data. And though net interest paid began increasing slowly thereafter, the bite has been negligible; net costs rose around $86 billion over five years while nonfinancial corporate profits boomed by about $1.2 in the same period to around $2.7 trillion before taxes.
这打破了货币政策传导机制中的一个关键环节,该机制认为资本成本上升会抑制企业投资和招聘。这相当于影响1400万借款人的“抵押贷款锁定”故事的企业版,这些借款人在利率为2%至3%时重新贷款了房贷。现在,利息支出似乎又要成为一个因素了,而且有些突然。
This broke a key link in the chain of monetary policy transmission, in which higher costs of capital are thought to disincentivize business investment and hiring. It was the corporate version of the great mortgage lock-in story affecting 14 million borrowers who refinanced home loans when rates were 2% to 3%. Now, somewhat suddenly, interest expense is set to become a factor again.
CoreWeave可以被视为信贷矛尖的尖端,因为其商业模式依赖于持续进入债务市场。该公司的增长建立在这样一个前提:它能够定期以合理利率借款,购买更多AI芯片并建设更多数据中心,然后通过长期合同出租,产生高于其资本成本的回报。前期借款对于实现后来的现金流承诺至关重要。
CoreWeave can be considered the tip of the credit spear, since its business model relies on continual access to debt markets. The company’s growth is premised on the idea that it can regularly borrow at reasonable rates to buy more AI chips and build more data centers, which it can then rent out through long-term contracts, generating returns higher than its cost of capital. The up-front borrowing is essential to fulfill the promise of the cash flows later.
CoreWeave的债券和股价上周在没有明显催化剂的情况下崩溃,唯一的背景是长期政府债券收益率普遍上升。市场研究公司Gartner Inc.的一份报告也加剧了悲观情绪,该报告称AI收入可能无法证明数据中心投资规模的合理性。
CoreWeave’s bonds, and its stock price, collapsed last week without an obvious catalyst except for the general rise in long-term government bond yields. Also exacerbating poor sentiment was a note from market research firm Gartner Inc., which said that AI revenue might not justify the scope of the data center investment.
虽然CoreWeave的情况属于极端个例,但它已引发了整个市场的担忧。由于美国国债收益率持续攀升,加之投资者要求更高的风险补偿,甲骨文公司、谷歌母公司Alphabet以及Meta平台公司的借贷成本均出现上升。目前美国的财政赤字规模约占国内生产总值的6%,且预计将维持在这一水平,因此很难想象会影响其他借贷成本的国债收益率会在短期内大幅下降。
While CoreWeave is an extreme example, it has sent concern rippling through the broader market. Oracle Corp., Alphabet Inc. and Meta Platforms Inc. are among those seeing their borrowing costs increase due to rising US Treasury yields and investors demanding greater compensation for credit risk. And with fiscal deficits around 6% of gross domestic product and expected to hover there, it’s hard to imagine Treasury yields, which influence other borrowing costs, dropping a lot anytime soon.
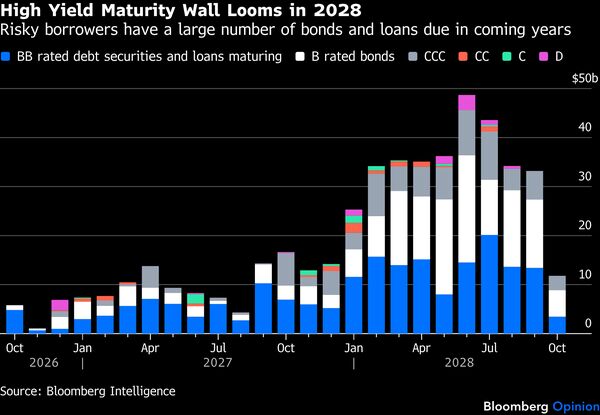
在彭博美国高收益债券指数所涵盖的债券发行方中,约四分之一的企业在未来一到三年内将面临债券到期的情况,这一比例已接近历史最高水平。2028年将是考验最为严峻的一年,届时大量债券集中到期,高企的收益率无疑会给这些企业带来沉重负担。
Around a quarter of constituents on the Bloomberg US High Yield index have bonds coming due in the next one to three years, near the highest on record. Elevated yields will be particularly hard to swallow in 2028, when the maturity wall looks most daunting.
对于信用评级较高的发行方而言,借贷成本上升带来的压力相对可控。关键在于企业会如何调整投资计划。例如,那些有望实现年均50%回报率的AI项目,无论投资级债券收益率是5%还是6%,都必然会继续推进。而那些盈利前景不明朗、风险较高的项目则很可能因高借贷成本而被迫搁置。
Among high-grade issuers, the borrowing-cost adjustment looks more manageable. There, it’s a question of how much companies might pare investment plans. AI projects with a 50% annual return potential, for instance, will no doubt proceed, irrespective of whether investment grade yields are 5% or 6%. Less profitable and more uncertain undertakings will probably have to wait if high borrowing costs are sustained.
正如米尔顿·弗里德曼所言,货币政策的效果往往存在“漫长且多变的滞后期”,不过这种滞后通常不会持续太久。首先,近几十年来企业信贷渠道从未出现过如此长时间的运转不畅;其次,当前货币政策效果还受到其他因素的干扰:自2019年以来,股市的强劲表现使得美国家庭净财富增加了78万亿美元,显著提升了消费者的购买力;而类似战时状态的巨额财政赤字也起到了缓冲经济下滑的作用。
Monetary policy has always operated with “long and variable lags,” as Milton Friedman put it, but rarely long. First, the corporate credit channel hasn’t looked broken for such a sustained period for decades. Second, this is occurring in the context of other distortionary impacts on the effects of monetary policy: A generational equity-market rally has generated $78 trillion in additional household net wealth since 2019 and bolstered consumer buying power, and war-time-style fiscal deficits have further cushioned growth.
这种企业债券收益率的上升,难道不是美联储自2022年以来一直期待的结果吗?从某种意义上说确实如此。但这并不意味着新任美联储主席凯文·沃什及其团队能够完全掌控最终结果。
Isn’t this rise in corporate yields what the Fed wanted and has been waiting for since 2022? In a sense. But that doesn’t mean that policymakers, under new Chair Kevin Warsh, have full control over the outcome.
一种良性的紧缩,在半导体及其他数据中心组件的供应短缺追赶上来的同时,放缓人工智能资本支出的繁荣,或许正是美国经济在连续近六年未能达标后,将通胀带回美联储2%目标所需要的。不可取的是信用利差无序扩大,将2028年到期墙从具有挑战性变得彻底无法应对,引发破产潮和失业潮。另一个风险是,此类事件会在短时间内抹去大量家庭财富积累。我们不知道会得到哪种结果。
A benign tightening that slows the AI capital expenditures boom while supply shortages in semiconductors and other data center components catch up might be just what the US economy needs to return inflation to the Fed’s 2% target after nearly six long years of missing it. What isn’t desirable is a disorderly widening of credit spreads that moves the 2028 maturity wall from challenging to downright unmanageable, triggering a wave of bankruptcies and unemployment. A further risk is that such an event would undo much of the household wealth accumulation in short order. We don’t know which outcome we will get.
这就是为什么政策制定者应谨慎推进进一步加息,在10月会议上将利率维持在3.75%-4%,并审慎权衡12月的决定。既然CoreWeave已经唤醒了沉睡的信用市场这头巨兽,很难预知它在未来几个月将如何反应。
That’s why policymakers should proceed slowly with further rate hikes, holding rates at 3.75%-4% at their October meeting and weighing the December decision carefully. Now that CoreWeave has awakened the sleeping giant that is the credit market, it’s hard to know how it will react in the months ahead.