唐纳德·特朗普重新上任,铜价因全球库存因他可能对金属征收关税而重新调整而出现剧烈波动。但随着特朗普进入第二个任期的中期,市场上众多看涨派开始担忧,如果他不兑现承诺,价格可能会暴跌。
Donald Trump came back into office, copper has surged on a seismic reshuffling of global inventories linked to the risk that he’ll impose tariffs on the metal. But as Trump nears the halfway mark on his second term, the market’s many bulls are growing wary that prices could crash if he doesn’t follow through.
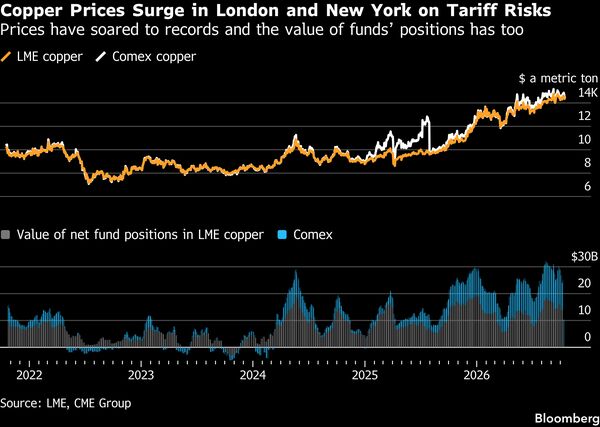
直到过去几周,纽约的铜期货一直以持续的溢价交易,高于伦敦金属交易所设定的全球基准价,这使得交易员能够在任何关税生效之前,通过将铜运往美国获得前所未有的利润。反过来,美国境外的库存急剧下降,持续的美国进口推动了一个反馈循环,帮助推动LME价格上个月升至每公吨近15,000美元的历史高点。
Until the past few weeks, copper futures in New York had traded at persistent premiums to the global benchmark set on the London Metal Exchange, and that’s enabled traders to make unprecedented profits shipping copper to the US before any levies come in. In turn, inventories outside the US have plunged, with ongoing US imports fueling a feedback loop that helped drive LME prices to a record near $15,000 a metric ton last month.
但随着中期选举临近,各市场的投资者开始质疑,民主党若表现强势是否会打乱特朗普的贸易议程——或者是否可能促使他加倍加征关税。而对于铜看涨派来说,如果特朗普被发现不愿意或无法推进这些关税,后果可能是深远的。
But with the midterm elections approaching, investors across markets are questioning whether a strong showing for the Democrats will disrupt Trump’s trade agenda — or whether it might even prompt him to double down on tariffs. And for copper bulls, the consequences could be profound if Trump is found to be unwilling or unable to push ahead with the levies.
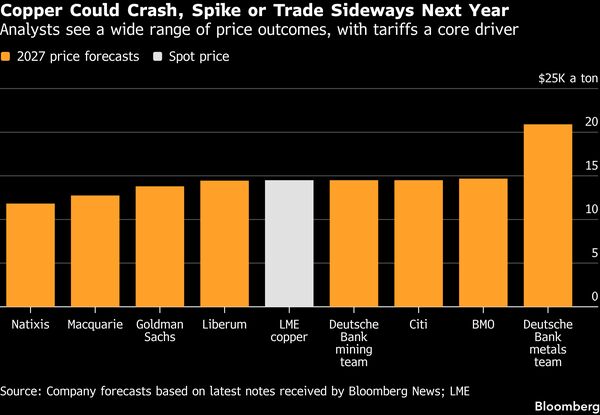
法国兴业银行(Natixis SA)的分析师警告称,关税交易已经在全球最重要的工业商品之一的市场中制造了一个泡沫,如果关税被取消,这个泡沫可能很快就会破裂。麦格理集团表示,在这种情况下,价格可能暴跌至每吨10,000美元;如果关税宣布滞后,给交易员留出更多时间将更多金属运往美国,价格也可能飙升至每吨18,000美元。
Analysts at Natixis SA have warned that the tariff trade has created a bubble in the market for one of the world’s most important industrial commodities, and it could soon burst if tariffs are ruled out. Macquarie Group says prices could crash toward $10,000 a ton in that scenario, or they could rally as far as $18,000 if tariffs are announced with a lag that would allow traders to ship even more metal to the US.
“我以前从未见过这样的情况,未来价格的走势最终取决于一个人的决定,”麦格理大宗商品策略师爱丽丝·福克斯在接受采访时说道。
“I have never seen anything like this before, with the future price direction ultimately resting on the decision of one man,” Alice Fox, a commodities strategist at Macquarie said in an interview.
随着中期选举临近,交易员们似乎越来越愿意押注反对关税,他们的赌注集中在纽约商品交易所(Comex)铜期货与伦敦金属交易所(LME)铜价之间的价差上。此前,这两个市场的走势基本同步,但自特朗普于2025年2月首次正式提出对铜征收关税以来,Comex价格——若特朗普实施关税,则该价格将包含关税成本——一直以巨大溢价交易于LME之上。
As the midterms approach, there are signs that traders are increasingly willing to bet against tariffs, with their wagers centered on the spread between copper futures on New York’s Comex and the LME. The two markets used to move in near-lockstep, but Comex prices — which would be inclusive of duties if Trump introduces them — have traded at huge premiums over the LME since Trump first formally proposed tariffs on copper in February 2025.
交易员可以通过卖出Comex合约、买入LME合约来使两市价格回归同步,但据Sucden Financial Ltd.首席执行官Marc Bailey透露,直到最近,这种套利活动几乎已完全停止。Sucden Financial Ltd.是该市场规模最大的经纪公司之一。这是因为,若特朗普确实推进关税政策,持有卖出Comex合约的交易员可能面临巨额亏损。
Traders can sell Comex and buy LME contracts to bring the markets back into line, but until recently, such arbitrage activity had dropped off almost entirely, according to Marc Bailey, the Chief Executive of Sucden Financial Ltd., one of the market’s largest brokerages. That’s because traders who’ve sold Comex contracts could face large losses if Trump does push ahead with tariffs.
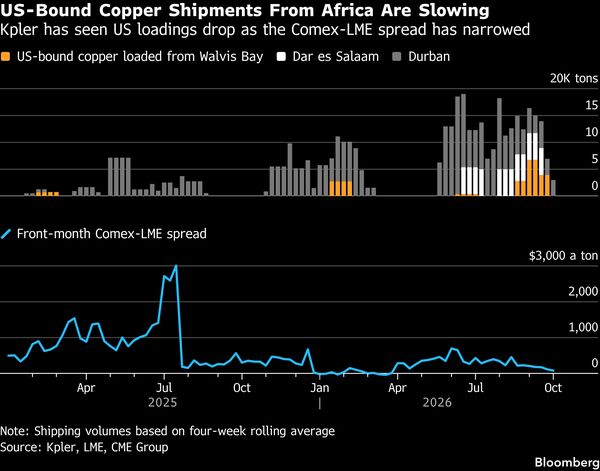
然而,近年来几周,Sucden一直在接到投资者的咨询,这些投资者对该交易重新产生了兴趣。同期,Comex与LME价格之间的价差出现急剧收窄,且在上月路透社的一则报道后,这一下跌趋势进一步加速——报道称,特朗普的铜关税计划因对其通胀影响的担忧而搁置。
But in recent weeks, Sucden has been fielding inquiries from investors taking a renewed interest in the trade. Over the same period, the spread between Comex and LME prices has collapsed, with the decline accelerating after a Reuters report last month stating that Trump’s plans for copper tariffs had stalled due to concerns about their inflationary impact.
“在过去几周里,市场情绪似乎发生了一点变化,”Bailey在伦敦接受采访时表示。“人们开始考虑重新尝试涉足这一交易。”如果这一趋势继续升温,投资者通过Comex价差押注反对关税的意愿增强,可能对市场产生重大影响,因为这将持续削弱交易员向美国运输更多金属的激励。
“In the past few weeks, the mood seems to have shifted a bit,” Bailey said in an interview in London. “People are starting to consider dipping their toes back in.”If the trend gathers steam, investors’ growing willingness to bet against tariffs via the Comex spread could have major consequences for the market, by continually negating the incentive for traders to ship more metal to the US.
在实物铜市场,随着Comex价差的收窄,非洲向美国运输的铜货量已经在减少,这一数据来自船舶追踪公司Kpler。而尽管对关税的疑虑在增加,交易员们也在关注一个不确定因素:特朗普可能在中期选举之后、在他们船只抵达美国港口之前宣布关税。
In the physical copper market, US-bound shipments of copper from Africa are already dwindling as the Comex spread collapses, according to data from ship-tracking firm Kpler. And while doubts about tariffs are growing, traders are also mindful of the wildcard possibility that Trump will announce tariffs right after the midterms, and before their vessels land.
随着伦敦金属交易所(LME)一年一度的LME Week聚会本周末在伦敦拉开序幕,Comex价差的崩溃正为一场辩论添柴加火:在能源价格飙升、利率上升和股市动荡威胁需求前景的背景下,铜价是否会受到重力影响而回落。
As the metals industry’s annual LME Week gathering kicks off in London this weekend, the collapse in the Comex spread is adding fuel to the debate about whether gravity might catch up with copper as surging energy prices, rising interest rates and a faltering stock market pose threats to the demand outlook.
随着这些风险的加剧,美国与世界其他地区供应动态的对比正为交易员卖出Comex价差提供另一个动力,Marex Group(另一家主要金属经纪公司)的金属策略师Alastair Munro如是说。
As those risks grow, the contrasting supply dynamics in the US and the rest of the world are offering another incentive for traders to sell the Comex spread, according to Alastair Munro, a metals strategist at Marex Group, another major metals brokerage.
最近,LME的供应限制日益加剧,导致近月合约价格相对于Comex合约上涨,两者在临近到期时的价差逐渐缩小。例如,9月交割合约在交割前一个月内每吨下跌超过600美元,而Comex的结算价溢价降至4美元以下。
Recently, the LME’s growing supply constraints have caused front-month prices to rise relative to those on Comex, narrowing the gap between the two contracts as they approach maturity. The September-delivery contract, for instance, shed more than $600 a ton in the month before delivery, with Comex settling at a premium of less than $4.
“由于套利空间在临近交割时自然倾向于收敛,因此卖出纽约、买入伦敦的意愿更强,”Munro在伦敦通过电话表示。“套利只是这种现象的一种表现,但基于宏观面悲观的预期,交易员普遍更倾向于做空铜。”当然,铜交易员曾因特朗普的关税政策而判断失误,最痛苦的一次发生在去年7月,当时他对下游铜产品征收了50%的关税,但未触及在期货市场交易的商品级铜。
“There’s greater appetite to sell New York and buy London because there’s a natural predilection for the arb to close as it comes into prompt,” Munro said by phone from London. “The arb is one manifestation of it, but there’s a growing eagerness to be short copper more generally on a bearish macro view.”To be sure, copper traders have been badly wrong-footed by Trump on tariffs before, most painfully in July last year, when he introduced 50% levies on downstream copper products while leaving the commodity-grade form of the metal traded in futures markets untouched.
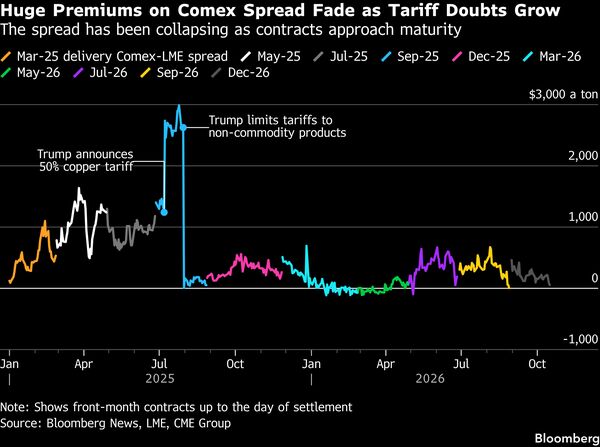
这导致Comex价格暴跌,但直到最近,Comex价格仍一直高于LME价格,因为特朗普曾表示未来可能实施此类关税。自那以后,铜市一直陷入一场两极化的辩论之中:特朗普究竟会不会在未来对铜征收关税。
That sent Comex prices crashing, but until recently they’ve remained at a substantial premium to the LME because Trump left the door open to imposing them in future. Ever since, the copper market has been in the grips of the polarizing debate over whether he will.
随着对关税的疑虑日益增加,铜市场中寥寥无几的人期待他能够完全取消关税,因为这样做可能会导致美国港口累积的巨量库存涌回国际市场。一种流行的观点认为,特朗普对关税保持沉默是一种有意的策略,旨在制造“战略模糊性”以防止这种情况发生。
While doubts about tariffs are growing, few in the copper market expect him to rule them out entirely, because doing so could allow the vast stockpiles that have accumulated in US ports to flood back out into international markets. One popular theory is that Trump’s silence on tariffs is a deliberate ploy to create ‘strategic ambiguity’ to prevent that.
但考虑到关税在特朗普政治议程中的核心地位,仍有人期待他将继续推进 — — 可能早在今年1月1日,正如去年商务部向特朗普提供的建议所指示的那样。
But given how central tariffs have been to Trump’s political agenda, some still expect him to push ahead — potentially as soon as Jan. 1, in line with advice given to Trump last year by the Commerce Dept.
“关键的不确定性在于美国的关税政策,”上海杜诚私募基金管理有限公司投资总监李格斯说。“由于缺乏对政府思路的可见性,无论是做多还是做空铜,都难以提出一个直接的方向性论点。”目前,美国的铜库存已经如此庞大,以至于制造商可能需要数年时间才能消化。与此同时,过剩供应为交易商创造了一个罕见的机会:他们可以买入库存,并通过在COMEX卖出期货合约来锁定微薄利润。
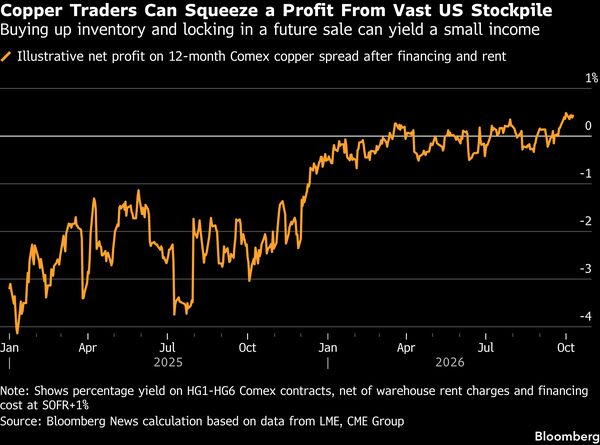
“The key uncertainty is US tariff policy,” said Grace Li, investment director of Shanghai Ducheng Private Equity Fund Management Co. “With little visibility into the administration’s thinking, it is difficult to make a straightforward directional case for either going long or short copper.”Already, the US’s copper stockpile is so vast that it could take years for manufacturers to work through. In the meantime, the oversupply has created a rare opportunity for traders to buy up inventories and lock in a small profit by selling futures contracts on Comex.
这些所谓的 contango 融资交易正在为围绕供应动态以及明年价格前景的讨论增添更多复杂性。
These so-called contango financing deals are adding further complexity to the debate surrounding supply dynamics and the outlook for prices going into next year.
与美国进口贸易创造的丰厚机遇相比,这些交易提供的利润微乎其微。但它们仍然足够有利可图,以至于美国银行公司(Bank of America Corp.)的分析师表示,这可能会阻止铜流回全球市场 — — 即使特朗普在关税问题上让步,也有助于支撑价格。
The profits on offer are meager compared to the bonanza opportunities created by the US import trade. Still, they’re lucrative enough that analysts at Bank of America Corp. say it could keep copper from flowing back out into the global market — helping keep prices propped up even if Trump does back down on tariffs.
而对于任何持看跌铜观点的人来说,特朗普推进关税的风险仍然巨大。根据商务部的建议,这些关税可能会分阶段实施 — — 2027年为15%,2028年为30%。
And for anyone taking a bearish view on copper, the risk that Trump will move ahead with tariffs still looms large. Under the Commerce Dept.’s recommendation, the levies could be introduced in phases, set at 15% in 2027 and 30% in 2028.
这可能意味着铜将继续被拉入美国,重新点燃全球竞拍战,推高铜价至历史新高。在主要消费国中国,库存已被积极抽减,若中国被迫在美进口激增的同时重新补库,价格可能急剧上涨。
That could mean copper will keep getting pulled into the US, reigniting the global bidding war that’s lifted copper to record highs. In top consumer China, inventories have already been drawn down aggressively, and if they’re forced to restock at the same time as US imports are surging, prices risk corkscrewing higher.
“他们可能以为,到现在这场囤积已经结束了,”BMO资本市场有限公司商品分析师海伦·阿莫斯(Helen Amos)表示。“如果他们认为:‘实际上,这还会持续两年?’”
“They probably thought that this whole stockpiling would be done by now,” said Helen Amos, a commodities analyst at BMO Capital Markets Ltd. “What if they think: ‘Actually, this is going to go on for another two years’?”