根据彭博社对政府债券交易商的调查,英国本财年将需要比原计划多借入 34 亿英镑(约合 45 亿美元),以应对更高的债务成本和公共支出。
The UK will need to borrow £3.4 billion ($4.5 billion) more than previously planned this fiscal year to cover higher debt costs and public spending, according to government bond dealers surveyed by Bloomberg.
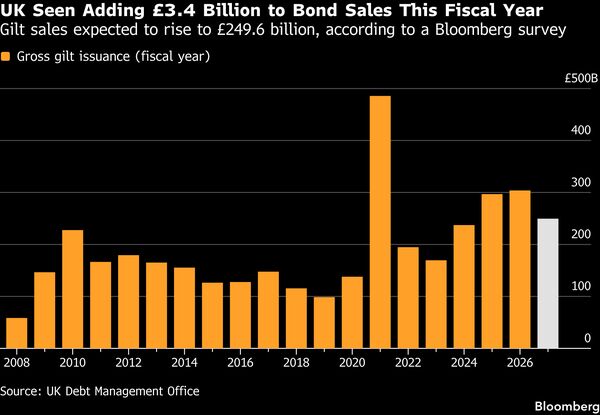
10 位受访者的中位数估计显示,截至 3 月止的本财年英国国债发行量将达 2496 亿英镑,预测区间为 2430 亿至 2562 亿英镑。债务管理办公室 4 月宣布的发行量为 2462 亿英镑。
The median of 10 estimates puts gilt issuance at £249.6 billion in the year through March, with forecasts that ranged from £243 billion to £256.2 billion. That compares with £246.2 billion announced by the Debt Management Office in April.
借款需求上升反映出,随着收益率飙升,安迪·伯纳姆领导的新政府财政空间大幅收窄。英国领导人面临压力,既要缓解家庭不断上涨的能源账单,又要增加国防开支,而更高的借贷成本让他们的腾挪余地更小。
The higher borrowing needs reflect sharply reduced fiscal room for Andy Burnham’s new government as yields surge. UK leaders are under pressure to cushion households from rising energy bills and increase defense spending, even as higher borrowing costs leaves them less room to maneuver.
一级交易商的中位数估计显示,财政缓冲空间将缩减约三分之一,降至 152 亿英镑,政府通过增税(如提高英国银行税)部分抵消了这一下降。
The median estimate among primary dealers is for the headroom to fall around a third to £15.2 billion, as the government partially offsets some of the decline through taxes, such as an increase in UK bank levies.
自伊朗战争爆发以来,英国 10 年期基准国债收益率已从 4.23% 升至 5.4%。
Benchmark 10-year UK yields have risen to 5.4% from 4.23% since the outbreak of the war in Iran.
这使政府更接近触及其主要财政规则红线,该规则要求到本届议会结束时,日常开支须由税收收入覆盖。
That’s brought the government closer to bumping up against its main fiscal rule, which requires day-to-day spending to be covered by tax receipts by the end of the Parliament.
更新后的发行额度将随政府于 10 月 28 日提交伯纳姆和财政大臣约翰·希利执政后的首份预算案而出台。即使有这笔额外借款,发行量仍将低于 2025-26 财年的 3040 亿英镑。
The updated remit will come as the government delivers its first budget under Burnham and Chancellor John Healey on Oct. 28. Even with the extra borrowing, issuance would drop from £304 billion in the 2025-26 financial year.
法国巴黎银行策略师凯瑟琳·尹等人撰文称,预计预算案将遵守财政规则,避免任何可能扰动“本已脆弱的英国国债市场”的意外情况。
BNP Paribas expects the budget to stick to the fiscal rules and avoid any surprises that could unsettle “an already fragile gilt market,” strategists including Katherine Yoon wrote.
与前几年的大幅超发相比,此次额外借款规模属于温和水平。2025 年 11 月发行额度曾扩大 46 亿英镑,2024 年 10 月更曾激增 192 亿英镑。
Relative to big overshoots of previous years, the extra borrowing would be moderate. In November 2025 the issuance remit was expanded by £4.6 billion. In October 2024, it ballooned by £19.2 billion.
英国债务管理局预计将更多地依赖短期金融工具来填补资金缺口,发行110亿英镑的国库券,高于根据中位数估算在4月份预测的50亿英镑。
The DMO is expected to lean more on short-dated instruments to fill the gap, issuing £11 billion Treasury bills, higher than the £5 billion forecast in April, based on the median estimate.
美国银行利率策略师阿格内·斯滕盖里特和马克·卡普莱顿表示:“我们预计英国债务管理局将对期限结构做出更有意义的调整。这将使供给与需求更好地匹配。”根据9家交易商的反馈,除了更多地使用国库券外,英国债务管理局还将利用短期国债满足42.7%的发行需求。它将用中期国债满足35.1%的资金需求。相比之下,英国债务管理局4月份预测的国债销售中,短期国债占39%,中期国债占31%。
“We expect the DMO to make more meaningful adjustments to the maturity mix,” said Agne Stengeryte and Mark Capleton, rates strategists at Bank of America. “This would better align supply with demand.”As well as a greater use of T-bills, the DMO will tap short maturities for 42.7% of issuance, based on responses from nine dealers. It will meet 35.1% of its needs with medium-dated gilts. This compares to DMO forecasts in April for 39% of gilt sales to be short and 31% medium-dated.
据交易商预计,长期国债的供应量将降至6.6%。今年迄今为止,长期债券仅发行了一次,即9月8日发行的价值42.5亿英镑的30年期债务。今年年初,英国债务管理局曾预测,在2026至2027财年的国债销售中,长期国债将占9%。
Long-dated supply is expected to fall to 6.6%, according to the dealers. So far this year, there’s only been one sale of long bonds, £4.25 billion of 30-year debt on Sept. 8. At the start of the year the DMO forecast 9% of 2026-27’s gilt sales on the long end.
英国政府的加权平均债务期限仍为11年,在七国集团同行中是最长的,尽管英国债务管理局近年来一直在缩短这一期限。英国央行也已在其量化紧缩计划下停止出售2049年后到期的国债,从而减少了长期端的供应。
At 11 years, the UK government still has the longest weighted-average maturity among Group-of-Seven peers, though the DMO has been shortening it in recent years. The Bank of England has also ended sales of gilts maturing after 2049 under its quantitative-tightening program, reducing supply at the long end.