美联储的抗通胀斗争正面临一个日益棘手的复杂因素:房地产市场正在低迷,而更广泛的价格压力依然存在。
The Federal Reserve's inflation fight is running into a growing complication: The housing market is slumping even as broader price pressures persist.
周二发布的多份独立报告显示,9月份的房地产数据进一步恶化,这增加了央行在考虑下一步利率举措时面临的、本已错综复杂的政策环境。
Housing data deteriorated further in September, according to separate reports Tuesday, adding to an already complicated policy landscape for the central bank as it contemplates its next move on interest rates.
形势似乎将在好转前进一步恶化。如果美联储如预期那样在未来几个月内加息,已经达到7.43%的抵押贷款利率可能会进一步走高,进一步打击住房负担能力。较高的住房借贷成本伴随着通胀的普遍上升和住房短缺同时出现。
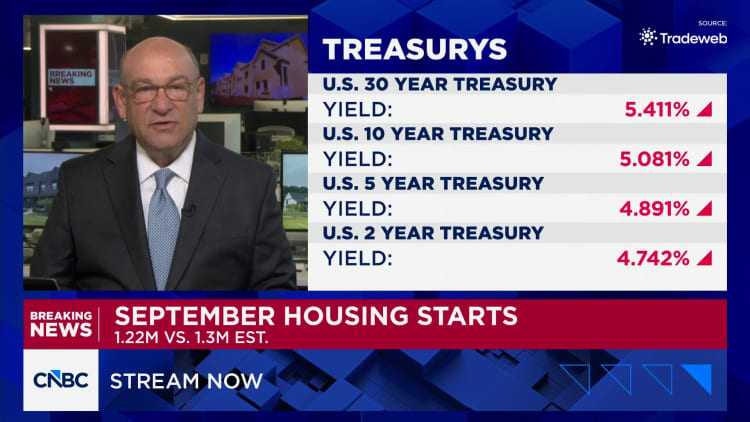
Things appear poised to get worse before they get better. If the Fed raises short-term rates as expected over the next several months, mortgage rates that are already at 7.43% could push even higher, putting a further damper on affordability. Higher home borrowing costs have coincided with a general rise in inflation and a housing shortage.
Fwdbonds首席经济学家克里斯·鲁普基写道:“除非华盛顿能在政策上来个180度大转弯,让新房成本变得更负担得起,否则房地产市场即将进入深度休眠。虽然还没到冬天,但房地产市场正进入深度冻结。” 全国房地产经纪人协会报告称,作为一项衡量已签约但未完成交易的房屋销售的前瞻性指标,成交合同指数跌至2001年有记录以来的历史最低点。该指数环比下滑7.3%,同比下降11.3%。华尔街的预估仅为下降0.4%。
"The housing market is about to go into a deep sleep unless Washington can do a 180 on its policies and make the cost of a new home more affordable," wrote Chris Rupkey, chief economist at Fwdbonds. "It is not winter yet but housing is going into a deep freeze." The National Association of Realtors reported that pending sales, a forward-looking index that measures home sales under agreement but not completed, hit an all-time low in records that stretch back to 2001. The index slid 7.3% for the month and was off 11.3% from a year ago. The Wall Street estimate was for a decline of just 0.4%.
周二公布的另一项评估市场状况的重要指标——新房开工数,也录得远超预期的降幅,而预期本身已相对悲观。
Housing starts, another important metrics when evaluating the state of the market, also posted a decline well outside already-muted expectations Tuesday.
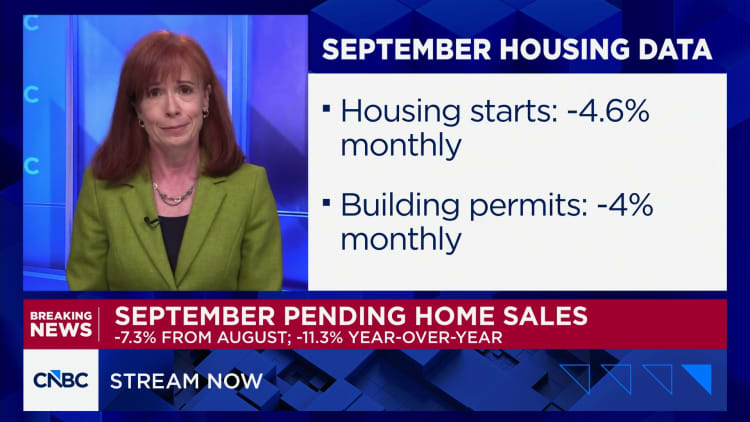
根据商务部数据,经季节性调整的年化率计算,私营新房开工数环比下降5.2%,预期仅为下降0.4%;建筑许可证下降0.2%,而道琼斯共识预期为增长2%。
Privately owned housing starts fell at a seasonally adjusted annualized rate of 5.2% on the month, against expectations for a decline of just 0.4%, while building permits were off 0.2%, against the Dow Jones consensus outlook for a 2% gain, according to Commerce Department data.
此外,独栋住宅许可证总数仅为84.5万份,较8月下降4%,为2023年以来的最低水平。
Moreover, single-family permits totaled just 845,000, down 4% from August and the lowest number since 2023.
“由于抵押贷款利率快速上升,9月份市场状况走弱,”全美房地产经纪人协会(NAR)首席经济学家劳伦斯·云(Lawrence Yun)表示。“尽管就业增长和收入增加可以支持购房,但住房负担能力更多地受到抵押贷款利率变化的影响。”利率上升令前景承压据《抵押贷款新闻日报》(Mortgage News Daily)数据,30年期抵押贷款利率在9月大部分时间里均高于7%,月末时在7.6%左右。
"Market conditions weakened in September due to fast-rising mortgage rates," said Lawrence Yun, the NAR's chief economist. "Although job growth and income gains can support home purchases, housing affordability is more affected by changes in mortgage rates." Rising rates weigh on outlook The rate for a 30-year mortgage was above 7% for most of September, ending the month around 7.6%, according to Mortgage News Daily.
五年前,利率接近3%,助推了新冠疫情时期的住房繁荣,当时需求激增,进而推高了房价。除待成交销售数据外,房屋建筑商信心处于14年来未见的低位。
Five years ago, rates were closer to 3%, feeding into the Covid-era housing boom that saw an explosion in demand and, consequently, prices. Outside of the pending sales number, home builder sentiment is at lows not seen in 14 years.
在某些条件下,美联储官员可能会以更宽松的货币政策应对住房疲软。降低利率通常通过降低借贷成本来刺激需求。
Under some conditions, Fed officials might respond to the housing weakness with easier monetary policy. Lower rates generally help spur demand by lowering borrowing costs.
但美联储在控制通胀方面面临更大的挑战。上周公布的消费者和生产者价格数据几未提供乐观迹象,批发最终需求商品价格上涨2.6%,涨速为劳工统计局(BLS)这一数据系列自2009年12月以来最快。
But the Fed has a bigger fight on its hands in its effort to bring inflation under control. Readings last week on consumer and producer prices provided few signs of optimism, with wholesale final demand goods prices rising 2.6%, the fastest pace in a Bureau of Labor Statistics data series going back to December 2009.
美联储官员表示,他们正在追踪对人工智能的强劲投资所带来的通胀效应,这正在推高芯片和电子产品的成本。同时,他们相信,人工智能投资带来的收益可能抵消住房等较疲软经济板块的影响。
Fed officials have said they are tracking the inflationary effects of the robust investment in artificial intelligence, which is driving up the cost of chips and electronics. At the same time, they believe that benefits from AI investment could offset weaker sectors of the economy such as housing.
然而,总体条件指向住房市场在企稳前可能进一步走弱,高盛经济学家罗尼·沃克(Ronnie Walker)周一在给客户的报告中表示。
However, conditions generally point to a housing market likely to weaken further before stabilizing, Goldman Sachs economist Ronnie Walker said in a client note Monday.
“我们预计,2027年,由近期抵押贷款利率反弹重新引发的可负担性逆风将日益占据主导地位,进一步拖累活动,”沃克写道。“持续较高的抵押贷款利率将继续对房屋周转率产生最显著的影响,近期利率的上涨可能会在未来几个月推低现有房屋销售。”
"In 2027, we expect the headwind from affordability—reignited by the recent rebound in mortgage rates—to increasingly dominate, weighing further on activity," Walker wrote. "Sustained higher mortgage rates will continue to have their most pronounced impact on housing turnover, and the recent run-up in rates is likely to push existing home sales lower in the coming months."
更多同类数据 数据点讲述了这一故事:超过95%的抵押贷款借款人拥有的利率低于现行水平,65%的借款人低2个百分点。高盛预测,未来三个季度住宅投资将分别下降2.5%、4%和1%,如果抵押贷款利率不下降,跌幅可能更陡峭。
More of the same Several data points tell the story: More than 95% of mortgage borrowers have rates below the prevailing level, and 65% are 2 percentage points below. Goldman forecasts residential investment to decline 2.5%, 4% and 1% respectively, over the coming three quarters, with a possibility for a steeper decline if mortgage rates don't fall.
该机构预计,2027年单户住宅开工量仅为87.5万套,与今年基本持平,而现有房屋销售预计为390万套,也与2026年大致相同,但显著低于新冠疫情前2019年水平的26%。沃克将这种中等水平归因于“锁定”效应,即现有房主因搬家并承担更高借贷成本过于昂贵而不愿移动,同时可负担性恶化拖累了新建住宅。
The firm sees single-family starts of just 875,000 in 2027, little changed from this year, while existing sales are forecast at 3.9 million, also about the same as 2026 but notably 26% below pre-Covid 2019 levels. Walker attributed the middling levels as a product of the "lock-in" effect in which it's too expensive for current homeowners to move and take on higher borrowing costs while deteriorating affordability weighs on new construction.
“近年来,住房活动一直保持在一定区间内,上行受限于可负担性逆风,下行则因长期存在的住房短缺而得到缓冲,”沃克写道。“2027年,我们预计可负担性逆风将日益占据主导地位,进一步拖累活动。”
"Housing activity has remained rangebound in recent years, capped on the upside by affordability headwinds and buffered on the downside by the longstanding housing shortage," Walker wrote. "In 2027, we expect the headwind from affordability to increasingly dominate, weighing further on activity."
市场预期美联储在下周会议上将维持基准利率不变。然而,根据芝商所“美联储观察”工具,期货定价暗示12月有很大可能加息25个基点,2027年3月再加息25个基点。
Markets expect the Fed to hold benchmark rates steady when it meets next week. However, futures pricing implies a strong chance of a quarter-point hike in December and another in March 2027, according to the CME Group's FedWatch tool.
一线乐观来自全美房地产经纪人协会经济学家云,他认为抵押贷款成本领先于美联储加息的趋势可能意味着利率正在见顶。
One point of optimism comes from Yun, the NAR economist, who thinks the trend of mortgage costs running ahead of Fed hikes could mean that rates are topping out.
他说:“考虑到抵押贷款利率的涨幅已经远超美联储短期利率的加息幅度,抵押贷款利率可能已触及顶峰。买家和卖家可能只是在观望,等待抵押贷款利率向有利方向变动。”
"Given that mortgage rates have already risen much more than the Federal Reserve's short-term interest rate hikes, mortgage rates could be topping out," he said. "Buyers and sellers may simply be holding back until mortgage rates move favorably."