法国正经历数十年来最严重的社会动荡,其借贷成本大幅飙升。法国国债收益率已升至近四分之一世纪以来的最高水平,投资者要求为持有法国政府债务获得更高的回报。这一飙升反映出债券市场日益形成的一种共识:借钱给法国正变得越来越有风险。
France’s borrowing costs have surged amid the worst social unrest in the country in decades. Yields on French bonds have risen to their highest levels in nearly a quarter of a century as investors demand higher returns for taking on government debt. The surge reflects a growing conviction in bond markets that lending to France is becoming an increasingly risky proposition.
法国正面临政府支出与收入之间不断扩大的缺口,而该国碎片化的政治格局在如何填补这一缺口的问题上存在严重分歧。
While France is grappling with a widening gap between government spending and revenues, the country’s fragmented political landscape is bitterly divided on how to plug the hole.
与此同时,数十万抗议者走上街头,反对拟议的预算削减,并要求在生活成本纾困以及教育等公共服务方面增加支出。部分抗议者参与了骚乱和抢劫。
Meanwhile, hundreds of thousands of protesters, some of whom have participated in rioting and looting, have taken to the streets to oppose proposed budget cuts and demand greater spending on cost-of-living relief and public services such as education. France’s national debt is now at its highest level since the immediate aftermath of World War II, nearing 120 percent of gross domestic product (GDP).
法国国家债务目前处于二战刚结束以来的最高水平,接近国内生产总值的120%。
Bonds are a type of loan to a government or corporation.
债券是向政府或企业提供贷款的一种形式。各国经常从债券市场借款,以支持税收收入无法覆盖的支出。
Countries routinely borrow from bond markets to allow spending that is not covered by tax revenues. In exchange for buying a bond, an investor is paid regular interest payments, plus the original borrowed sum at a set date in the future.
作为购买债券的交换,投资者会定期获得利息,并在未来某个约定日期收回最初借出的本金。在此期间,这些债券可以在债券市场上转让给其他投资者。债券价格受利率、通胀以及对发行人偿债能力的信心等因素影响。债券价格上涨时,收益率下降,反之亦然。
These bonds can be traded on the bond market to other investors in the meantime. Bond prices are influenced by interest rates, inflation and confidence in the issuer’s ability to repay the loan, among other factors. When bond prices rise, bond yields fall, and vice versa. France’s 10-year bond yield has risen more than 130 basis points since June, topping 4.9 percent.
法国10年期国债收益率自6月以来已上升逾130个基点,突破4.9%。
France’s borrowing costs now stand at their highest levels since 2002, swallowing up a growing share of tax revenues that could otherwise be directed towards essential services such as education and healthcare.
法国目前的借贷成本处于2002年以来的最高水平,吞噬了越来越大的税收份额,而这些资金原本可用于教育、医疗等基本公共服务。
While France’s debt levels are relatively high, the amount that a country owes is just one consideration for investors pricing the risk of its bonds.
尽管法国的债务水平相对较高,但对债券进行风险定价的投资者而言,一个国家的欠债规模只是考量因素之一。
Market confidence in a country’s ability to meet its obligations is shaped by a range of factors, including the economy’s strength, the amount of its external debt versus domestic debt and the ability of the political system to govern effectively.
市场对一个国家履行债务义务能力的信心,受到一系列因素影响,包括经济实力、外债与内债的比例,以及政治体系有效治理的能力。
“The sustainability of sovereign debt is rarely determined by its absolute level alone,” Victor Lequillerier, president of BSI Economics, a think tank in Paris, told Al Jazeera.
巴黎智库BSI Economics总裁维克多·勒基耶里耶对半岛电视台表示:“主权债务的可持续性很少仅由其绝对水平决定。”
“It depends far more on its trajectory, structure, and broader economic and financial context.”
“它更多地取决于债务的轨迹、结构以及更广泛的经济和金融背景。”就法国而言,该国政治体系的瘫痪是当前债券市场担忧的关键驱动因素。
In France’s case, the paralysis of the country’s political system is a key driver of concern in the bond markets currently. In the fragmented National Assembly, French Prime Minister Ssbastien Lecornu, who was appointed by President Emmanuel Macron under the country’s semi-presidential system, is mired in a legislative battle to pass a budget for next year that includes 54 billion euros ($61bn) in savings.
在分裂的国民议会中,法国总理塞巴斯蒂安·勒科尔尼正深陷一场立法之战,力图通过包含540亿欧元(610亿美元)节约措施的明年预算。勒科尔尼由总统埃马纽埃尔·马克龙在该国半总统制下任命。
Marine Le Pen of far-right National Rally and Jean-Luc Melenchon of far-left France Unbowed, the two leading candidates in next year’s presidential election, are opposed to Lecornu’s proposals, though the government could invoke a constitutional clause to bypass parliament if deemed necessary. Antonio Fatas, a professor of economics at INSEAD in Fontainebleau, France, told Al Jazeera: “Are the French numbers much worse than other countries? No, but marginally they are worse, and the real difficulty here is that the political situation is such that the current government does not have an easy path to put together a budget that makes sense from a debt sustainability point of view.”
极右翼国民联盟的玛丽娜·勒庞和极左翼“不屈法国”的让-吕克·梅朗雄是明年总统选举的两名领先候选人,他们都反对勒科尔尼的提案,不过政府若认为有必要,可以援引宪法条款绕过议会。
He added: “That’s what makes France a special case now, that’s why markets are very much worried about what France is going through and why you see a lot of the noise.”
法国枫丹白露欧洲工商管理学院经济学教授安东尼奥·法塔斯对半岛电视台表示:“法国的数字比其他国差很多吗?不,但边际上确实更差,而真正的困难在于,政治局势使得现任政府没有一条容易的路径来制定一份从债务可持续性角度看合理的预算。”
France’s national debt, at about 3.6 trillion euros ($4 trillion), is equivalent to 119 percent of GDP, up from 98 percent in 2019, the year before the start of the COVID-19 pandemic.
他补充说:“这就是为什么法国现在是一个特殊案例,这就是为什么市场对法国正在经历的情况非常担忧,也是为什么你会看到很多杂音。”法国的国家债务约为3.6万亿欧元(4万亿美元),相当于GDP的119%,高于2019年——即新冠疫情开始前一年——的98%。
Of greater concern to markets than the total debt is France’s ballooning deficit, however, which is expected to reach 5.4 percent of GDP in 2026 – far above the European Union average of just more than 3 percent. This is the amount by which a government’s spending exceeds its income.
然而,比总债务更令市场担忧的是法国不断膨胀的赤字,预计2026年将达到GDP的5.4%,远高于欧盟仅略高于3%的平均水平。赤字即政府支出超过收入的部分。
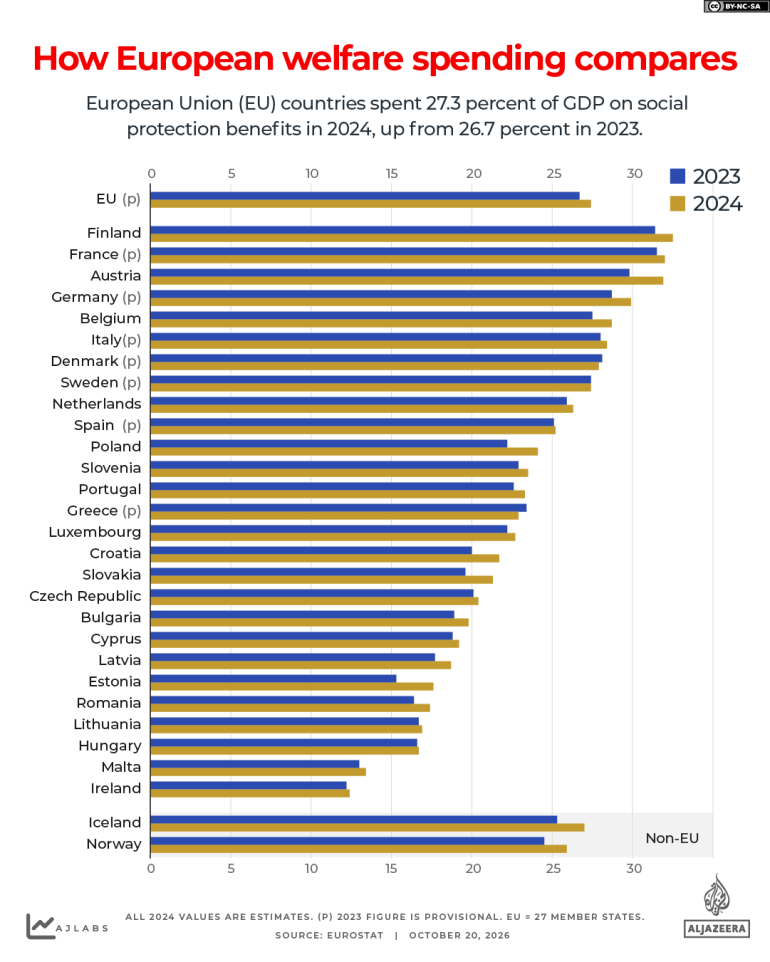
France, which has a strong tradition of left-wing politics and activism, has long had one of the biggest public sectors in the developed world. Government spending is equivalent to about 57 percent of GDP, second only to Finland among Organisation for Economic Co-operation and Development (OECD) countries.
法国有着浓厚的左翼政治和激进主义传统,长期以来一直是发达国家中公共部门规模最大的国家之一。
Public pensions make up a particularly large proportion of expenditure, amounting to 14 percent of GDP, a figure that is likely to rise as the country’s working-age population shrinks in the coming decades.
政府支出相当于GDP的约57%,在经济合作与发展组织(OECD)国家中仅次于芬兰。
“Ironically, President Macron has long discussed the reforms needed to improve the fiscal outlook and avoid attracting the ire of bond investors,” Alex Dryden, a macroeconomist at the Centre for Sustainable Finance at SOAS University of London, told Al Jazeera.
公共养老金在支出中占比尤其大,达到GDP的14%,而随着该国劳动年龄人口在未来几十年内减少,这一数字很可能进一步上升。
“From 2017 onwards, Macron has spoken of the need for pension reforms to ease the fiscal burden, but this is a lightning-rod political issue in France and attempts at reforms have stalled on multiple occasions.”
伦敦大学亚非学院可持续金融中心宏观经济学家亚历克斯·德莱登对半岛电视台表示:“具有讽刺意味的是,马克龙总统长期以来一直在讨论改善财政前景、避免招致债券投资者不满所需的改革。”
“Tackling this issue would resolve much of France’s fiscal burden, but that is much easier said than done,” Dryden added.
“自2017年以来,马克龙一直谈到需要进行养老金改革以减轻财政负担,但这在法国是一个极易引爆的政治议题,改革尝试已多次停滞。”“解决这一问题将化解法国的大部分财政负担,但说起来容易做起来难,”德莱登补充道。
While France levies some of the highest taxes of any country to support its sizeable welfare state, its budget deficit widened substantially during the pandemic and has remained above the recent historical trend ever since. Exacerbating the shortfall has been a long-running trend of anaemic growth, which saw the French economy expand by just 59 percent of the OECD average from 2000 to 2025.
尽管法国为支撑其庞大的福利国家而征收的税率在各国中属于最高之列,但其预算赤字在疫情期间大幅扩大,此后一直高于近期的历史趋势。
GDP is forecast to grow just 0.4 percent this year, following a 0.9 percent expansion in 2025.
长期低迷的增长趋势加剧了缺口——2000年至2025年间,法国经济仅增长至OECD平均水平的59%。
BSI Economics’ Lequillerier said the French government has spent years shirking the kind of budgetary reforms that reduced the deficits of heavily indebted peers such as Italy, Spain and Portugal.
继2025年增长0.9%之后,预计今年GDP仅增长0.4%。
“In the post-pandemic period, most European economies managed to normalise their fiscal positions and bring deficits closer to sustainable levels. France, however, failed to do so, with public spending growth persistently overwhelming revenue dynamics,” Lequillerier said.
BSI经济咨询公司的勒基利耶表示,法国政府多年来一直回避此类预算改革,而正是这类改革削减了意大利、西班牙和葡萄牙等负债沉重的同类国家的赤字。
Lequillerier said investors’ tolerance for the government’s lack of fiscal restraint has finally run out.
勒基利耶说:“疫情后时期,大多数欧洲经济体都设法实现了财政状况正常化,并将赤字降至更接近可持续的水平。然而法国未能做到这一点,公共支出增长持续压过收入增长势头。”勒基利耶表示,投资者对政府缺乏财政约束的容忍终于耗尽。
“The correction is becoming increasingly painful, and France risks isolating itself within the euro area as its principal fiscal underperformer,” he said. While relatively high, France’s debt is lower than that of several other economies, including the United States, Japan and Italy.
他说:“调整正变得越来越痛苦,法国作为欧元区主要的财政表现落后国,面临在欧元区内自我孤立的危险。”
But in each of those cases, there are specific circumstances that mitigate the risks.
法国的债务虽然相对较高,但低于其他几个经济体,包括美国、日本和意大利。但在上述每一个案例中,都有具体情况缓解了风险。
The US is better positioned than its peers to manage massive debt levels due to the status of the US dollar as the world’s primary reserve currency, which allows it to borrow money relatively cheaply and in greater amounts. Japan has been able to sustain a debt-to-GDP ratio of more than 200 percent because most of its debt is held by domestic institutions, insulating it from capital flight.
由于美元作为世界主要储备货币的地位,美国在管理巨额债务方面比其他国家处于更有利的位置,这使其能够以相对较低的成本借入更多资金。
Monetary authorities have also kept interest rates at ultralow levels.
日本之所以能够维持超过200%的债务与GDP之比,是因为其大部分债务由国内机构持有,从而免受资本外逃的冲击。货币当局还将利率维持在超低水平。
Italy’s debt-to-GDP ratio of 140 percent is higher than that of France, but it also has a smaller budget deficit equivalent to about 3 percent of GDP. “The total debt burden that a government can support depends on quite a few things and varies between countries,” Andrew Kenningham, chief Europe economist at Capital Economics, told Al Jazeera.
意大利的债务与GDP之比为140%,高于法国,但其预算赤字也更小,相当于GDP的约3%。
“For example, investors will get more anxious if the country’s economy is only slowly growing, or not at all, and if the government deficit is very high, which – all else equal – means the debt ratio will tend to rise. And the debt burden a country can support also depends on who wants to buy that country’s debt,” Kenningham said.
凯投宏观首席欧洲经济学家安德鲁·肯宁汉姆对半岛电视台表示:“政府能够承受的总债务负担取决于不少因素,并且因国家而异。”
France is also under pressure, in part, because there are more options in the bond market for investors to look at than in the past, said Lequillerier at BSI Economics.
肯宁汉姆表示:“举例来说,如果一国经济只是缓慢增长,甚至完全不增长,而且政府赤字非常高——在其他条件相同的情况下,这意味着债务比率往往会上升——投资者就会更加焦虑。一个国家能够承受的债务负担,还取决于谁愿意购买该国的债务。”
“Germany is now running larger deficits and issuing substantially more debt, while Italy and Spain have strengthened both their fiscal positions,” he said.
BSI经济研究所的勒基利耶表示,法国也面临压力,部分原因是如今债券市场上投资者可选择的投资对象比过去更多。
“France therefore faces much stiffer competition for international capital within the euro-denominated sovereign bond market.”
他说:“德国目前正在运行更大的赤字,并发行大幅更多的债务,而意大利和西班牙都强化了各自的财政状况。”
While France’s finances are far from unsalvageable, the longer the government takes to tighten its belt, the greater the risks of a full-blown debt crisis, economists say.
“因此,在欧元计价的主权债券市场内,法国在国际资本方面面临激烈得多的竞争。”经济学家表示,尽管法国的财政状况远未到无法挽救的地步,但政府收紧开支拖得越久,爆发全面债务危机的风险就越大。
“What is the likelihood of France going into a debt crisis? Enough that it should worry us,” INSEAD’s Fatas said. “As an economist, I could say the numbers are not too bad.”
欧洲工商管理学院的法塔斯说:“法国陷入债务危机的可能性有多大?大到足以让我们担忧。作为经济学家,我可以说这些数字还不算太糟。”他说:“我们可以找到一份能让法国处于更可持续状况的预算,但这需要某些妥协,需要某些政治选择,而在当前环境下,做到这些非常、非常困难。”
“We can find a budget that would put France in a more sustainable position, but that requires certain compromises, and that requires certain political choices, very, very difficult to do in the current environment,” he said. Lequillerier of BSI Economics said while a French default is not a realistic possibility, the country would suffer a “profound loss of economic credibility” if it had to seek assistance from an institution like the European Central Bank or the IMF.
BSI经济研究所的勒基利耶表示,尽管法国违约并非现实可能,但如果该国不得不向欧洲央行或国际货币基金组织等机构寻求援助,它将遭受“经济可信度的严重丧失”。
“This is not the central scenario today,” he said.
他说:“这不是今天的主要情景。然而,财政调整拖延得越久,这种结果就越不那么遥远。”
“Nevertheless, the longer fiscal adjustment is delayed, the less remote such an outcome becomes.”