贝莱德投资研究所表示,法国国债的剧烈抛售提醒人们,日益激烈的资本争夺战正使借款人面临更严格的审查,尤其是在高收益充斥的世界中。
The sharp selloff in French government bonds is a reminder that an intensifying battle for capital is putting borrowers under greater scrutiny, particularly in a world awash with high yields, according to the BlackRock Investment Institute.
虽然全球债券市场承压,但法国已成为薄弱环节,因为政府在试图推行削减成本的预算的同时,还要应对全国范围内关于生活成本和学校状况的抗议活动。
While bonds globally have come under pressure, France has emerged as a weak link as the government attempts to deliver a cost-cutting budget while grappling with nationwide protests over the cost of living and conditions in schools.
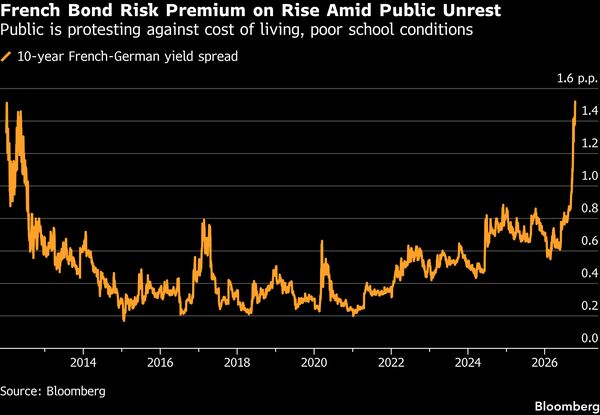
“法国国债抛售说明,在全球利率重置背景下,资本竞争正在重塑固定收益市场,”包括魏立在内的贝莱德策略师在一份报告中写道。“越来越重要的是,要了解是什么推动收益率上升,以及投资者是否得到了风险的充分补偿。”法国和德国10年期国债收益率差——这一备受关注的风险指标——周二已超过150个基点,这是自10月5日以来首次达到该水平。该利差最近触及159个基点的峰值,为该地区2011年主权债务危机以来的最宽水平。
“The French bond selloff illustrates how competition for capital is reshaping fixed income markets amid a global rate reset,” the BlackRock strategists including Wei Li wrote in a note. It’s “increasingly important to understand what is driving yields higher and whether investors are adequately compensated for the risks.”The spread between French and German 10-year yields, a closely-watched risk metric, passed 150 basis points on Tuesday, a level it last reached on Oct. 5. It recently hit a peak of 159 basis points, the widest since the region’s sovereign debt crisis in 2011.
“法国表明,精选很重要,”策略师写道。“与德国国债的利差扩大表明,投资者也在要求对法国的财政和政治风险给予额外补偿。”策略师表示,欧元区现在比15年前更有能力抵御危机。欧洲央行拥有更强大的工具,银行业也强大得多。贝莱德投资研究所指出,虽然法国的债务占GDP比率已膨胀至近120%,但整个欧元区的同等指标现在已回到2011年约89%的水平。
“France shows why selectivity matters,” the strategists wrote. “The widening spread over German bunds shows investors are also demanding additional compensation for France’s fiscal and political risks.”The euro area is much better equipped to weather a crisis now than 15 years ago, the strategists said. The European Central Bank has more powerful tools, and the banking sector is far stronger. While France’s debt-to-GDP has swollen to nearly 120%, the equivalent metric for the whole euro area is now back at its 2011 level of around 89%, BII noted.
然而,他们补充称,欧洲央行的干预“不是保证的”,“进一步的波动和溢出效应仍有可能”。贝莱德投资研究所表示,虽然无差别抛售可能在西班牙等公共财政状况更好的市场创造机会,但该机构对欧元区国债保持中立。
Yet intervention by the ECB “isn’t guaranteed” and “further volatility and spillovers remain possible,” they added. While indiscriminate selling could create opportunities in markets such as Spain, where public finances are in better shape, BII remains neutral on euro-area government bonds.
BII表示,欧洲以外也存在大量机会,全球超过80%的债券目前收益率高于4%,而五年前这一比例仅为6.3%。
There are also plentiful opportunities beyond Europe, with more than 80% of global bonds now yielding above 4% compared to just 6.3% five years ago, according to BII.
策略师们尤其看好美国国债——他们上周已上调了对其的评级——以及新兴市场本币债券,特别是拉丁美洲的此类债券。他们已削减了对日本政府债券的低配,因为他们认为,预期中的收益率调整现在很可能已基本完成。
In particular, the strategists favor US Treasuries — which they upgraded last week — and emerging market local currency debt, particularly in Latin America. They have trimmed an underweight on Japanese government bonds, with much of the anticipated yield adjustment having now likely played out, in their view.